The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Public liability and professional indemnity insurance can both be important for office-based businesses, but they respond to different types of claims. This guide explains the difference between third-party injury or property damage claims and claims connected to professional advice, errors, omissions or negligence.
Public liability and professional indemnity insurance are often discussed together, but they are not the same type of cover. For an office-based business, public liability generally relates to injury or property damage suffered by third parties, while professional indemnity relates to claims arising from professional services, advice, errors, omissions or alleged negligence.
Understanding the difference matters because a claim that appears to be a general business problem may fall under a specific policy type, or may not be covered if the business has chosen the wrong cover. This article explains how the two covers usually work, where they may overlap, and what Australian office-based businesses should consider when reviewing office insurance options.
Public liability vs professional indemnity: the core difference
The simplest distinction is the type of harm being alleged.
- Public liability insurance is generally designed for third-party personal injury or property damage connected with your business activities or premises.
- Professional indemnity insurance is generally designed for claims that your professional advice, service, design, recommendation, error or omission caused financial loss or another covered loss to a client or third party.
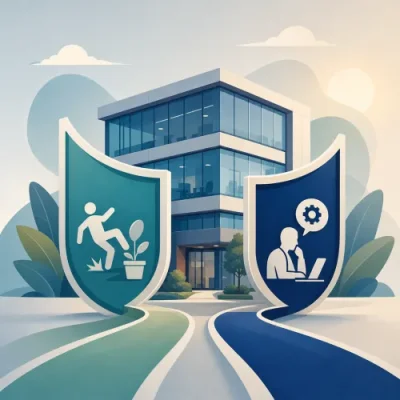
Both are forms of liability insurance for office businesses, but they respond to different risks. An office visitor tripping over a loose cable is usually a public liability issue. A client alleging your advice caused them a financial loss is usually a professional indemnity issue.
| Question | Public liability insurance | Professional indemnity insurance |
|---|
| What is the main risk? | Third-party injury or property damage | Claims arising from professional services, advice, errors or omissions |
| Who might claim? | Visitors, clients, suppliers, landlords or members of the public | Clients, customers or other parties affected by professional work |
| Common office example | A client slips in your reception area and alleges your business was responsible | A client alleges your advice, report or service contained an error that caused a loss |
| Commonly relevant to | Most businesses that interact with clients, visitors, suppliers or the public | Consultants, agencies, advisers, designers, technology firms and professional service providers |
| Policy trigger | Often connected to injury or damage occurring during the policy period, subject to policy wording | Often arranged on a claims-made basis, meaning timing, notification and retroactive dates can be important |
What office public liability insurance usually addresses
Office public liability insurance is commonly considered by businesses that have physical premises, receive visitors, attend client sites, hold meetings, run events, or interact with suppliers and members of the public. It may help respond to covered claims alleging that your business caused personal injury or property damage to someone else.
Examples may include:
- a client tripping over a loose mat or cable in your office;
- a supplier being injured while delivering equipment to your premises;
- an employee accidentally damaging a client's property while attending a meeting offsite;
- damage caused to a rented meeting space or shared workspace, depending on policy wording and exclusions.
Public liability may also include cover for legal defence costs where the claim is covered by the policy. However, exclusions, excesses, limits and conditions vary between insurers, so it is important to read the product disclosure statement and policy wording.
What professional indemnity insurance for an office business usually addresses
Professional indemnity insurance is generally relevant where a business provides professional advice, consulting, design, analysis, recommendations, documentation, strategy, technical services or specialist expertise. It may help respond to covered claims alleging that the business made an error, failed to deliver a required professional standard, omitted important information, or was otherwise negligent in providing professional services.
Examples for office-based businesses may include:
- a marketing agency being accused of providing campaign advice that caused a client financial loss;
- a business consultant being alleged to have made an error in a strategic report;
- an IT consultancy being accused of a professional mistake in a system specification or implementation plan;
- a design, engineering, accounting or advisory firm facing allegations that its professional work was inadequate or incorrect.
Professional indemnity policies often have detailed definitions of professional services, covered claims, exclusions and notification requirements. Some policies may also include or exclude specific types of liability, such as contractual liability, intellectual property matters, defamation, misleading or deceptive conduct, or cyber-related losses. The position depends on the policy and the circumstances of the claim.
Why office-based businesses often confuse the two
The confusion usually comes from the fact that both policy types deal with claims made by other people. They may also both involve legal costs, allegations of fault, and business activities that started in an office environment.
The key is to ask what the claim is actually about:
- Is the claim about bodily injury or physical property damage? Public liability may be the more relevant cover.
- Is the claim about professional work, advice, a service error or an omission? Professional indemnity may be the more relevant cover.
- Is there more than one allegation? More than one policy may need to be notified, depending on the circumstances and insurer requirements.
For example, if a client attends your office and is injured after slipping on a wet floor, that is different from a client alleging that your consulting advice caused them to lose a contract. Both situations may involve a client, but the nature of the alleged loss is different.
Examples of how the distinction works
Example 1: A visitor is injured at your office
A prospective client visits your office for a meeting. They trip over a box left in a walkway and suffer an injury. They allege your business failed to maintain a safe environment. This is the type of scenario commonly associated with public liability insurance, subject to the policy terms and the facts of the incident.
Example 2: A client alleges your advice caused a loss
Your business provides a written recommendation to a client. The client later alleges that the recommendation was wrong, incomplete or negligent and caused them financial loss. This is the type of scenario commonly associated with professional indemnity insurance, subject to the scope of professional services covered by the policy.
Example 3: A staff member damages a client's property during a meeting
An employee attends a client's office and accidentally damages equipment. Depending on the policy wording and circumstances, this may be considered under public liability because it involves damage to third-party property.
Example 4: A project deliverable contains an error
An agency prepares a client report, plan or technical document that allegedly contains a significant error. If the client claims the error caused them loss, the matter may be more closely connected to professional indemnity.
Do office businesses need both public liability and professional indemnity?
Some office-based businesses may need one, both or neither, depending on their activities, contracts, industry, premises arrangements and risk profile. There is no single answer that applies to every business.
Public liability may be relevant if your business:
- has clients, suppliers or visitors attending your office;
- works from a serviced office, coworking space or leased premises;
- attends client premises or public locations for work;
- runs workshops, presentations or events;
- has contractual obligations requiring public liability cover.
Professional indemnity may be relevant if your business:
- provides professional advice, consulting, recommendations or reports;
- delivers specialist technical, design, financial, marketing or management services;
- has clients who rely on your expertise to make decisions;
- is required by a client contract, tender, industry body or licence condition to hold cover;
- could face a claim if an error, omission or alleged negligence caused a client loss.
Startups and newer businesses should also consider how their liability exposures may change as they sign larger contracts, hire staff, move into premises or take on more complex professional work. For a broader planning guide, see our article on key office insurance policies for startups.
Important policy features to compare
When comparing public liability and professional indemnity cover, it is not enough to look only at the premium. Policy wording, exclusions, limits and conditions can have a major effect on how a policy may respond.
Limits of liability
The limit of liability is the maximum amount the insurer will pay for covered claims, subject to the policy terms. Businesses may need to consider contractual requirements, the scale of potential claims and whether defence costs are included within or in addition to the limit. Insurers and brokers may assess limits differently depending on the business and industry.
Excesses
An excess is the amount the business may need to contribute towards a claim. The excess can vary by policy type, claim type and insurer. A lower premium may sometimes be paired with a higher excess or narrower cover, so it is worth comparing the overall policy structure.
Exclusions
Exclusions set out what the policy does not cover. Public liability exclusions may differ from professional indemnity exclusions. Professional indemnity policies, in particular, may have detailed exclusions relating to known circumstances, contractual assumptions of liability, insolvency, cyber events, bodily injury or property damage, depending on the insurer and policy form.
Claims-made and notification requirements
Professional indemnity insurance is commonly written on a claims-made basis. This means cover may depend on when the claim is made and notified, and whether the relevant work falls within the policy's retroactive date and conditions. Businesses should understand notification requirements and keep records of circumstances that could later become claims.
Public liability policies often operate differently, but policy wording should always be checked. If an incident occurs, businesses should notify the insurer promptly and follow the policy's claim process.
Common gaps to watch for
Office-based businesses may assume a single business insurance policy covers every liability exposure. In practice, different risks may require different policy sections or separate policies. Common gaps include:
- having public liability cover but no professional indemnity cover, even though the business provides advice;
- having professional indemnity cover that does not accurately reflect the services the business now provides;
- relying on a landlord, coworking provider or principal contractor's insurance without understanding what it does and does not cover;
- failing to update cover after hiring staff, changing services or signing larger contracts;
- not checking whether client contracts require specific cover limits or policy types;
- assuming cyber, management liability, employment practices, contents or business interruption risks are covered by public liability or professional indemnity.
A broader office insurance review can help identify where liability cover fits alongside property, contents, cyber, business interruption and other policy types. Our office insurance checklist for Australian businesses provides a wider framework for reviewing these areas.
Questions to ask before choosing liability cover
Before arranging or renewing liability insurance, office-based business owners may find it useful to ask:
- Do clients, suppliers, landlords or the public visit our office?
- Do we visit client sites, run events or use shared workspaces?
- Do we provide advice, reports, designs, consulting, recommendations or specialist services?
- Could an error in our work cause a client financial loss?
- Do our contracts require public liability, professional indemnity or both?
- What services are listed in the professional indemnity policy schedule?
- Are defence costs included, and how do they interact with the policy limit?
- What exclusions are most relevant to our work?
- How do we notify circumstances or claims?
- Has our business changed since the policy was first arranged?
Because policy suitability depends on individual business circumstances and insurer criteria, many businesses choose to discuss their risks with a qualified insurance broker or adviser. You can use the brokers page to explore this next step if you need assistance comparing policy wording, exclusions or cover options.
How public liability and professional indemnity fit into office insurance
Public liability and professional indemnity are two important liability cover types, but they are not substitutes for each other. Public liability is generally about injury or property damage to third parties. Professional indemnity is generally about claims arising from professional services, advice, errors, omissions or negligence.
For many office-based businesses, the right approach is to identify how the business interacts with people, property and professional obligations, then compare policy options against those risks. The appropriate cover, limits and exclusions will depend on the business's services, contracts, clients, premises and insurer requirements.
This information is general in nature and does not take into account your objectives, financial situation or needs. Consider the relevant policy documents and seek professional advice where appropriate before making insurance decisions.
Published: Monday, 12th Oct 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.